Recover Unbilled Work in 13 Weeks with Service Business Accounting
Recover Unbilled Work in 13 Weeks with Service Business Accounting
The single most important change a service business must make to its accounting is to treat work delivered as earned revenue, not just cash-in-bank, and to tie time and project codes to every invoice. That means adopting accrual-aware bookkeeping with monthly work-in-progress (WIP) reconciliation instead of relying on a checkbook mentality. Start this week: build a 13-week cash forecast and reconcile last month’s WIP and accounts receivable before you do anything else.
TL;DR:
- Service firms must recognize revenue based on work delivered and tie every invoice to specific project and time codes, not just cash received.
- Tracking work-in-progress as a current asset reveals earned but unbilled revenue, preventing false profit reports and informing better staffing and pricing decisions.
- Implementing a strict monthly close, including WIP reconciliation, AR aging review, and bank matching, helps catch billing gaps and cash shortfalls early.
- Using integrated software that connects quoting, time tracking, invoicing, and accounting reduces manual errors and improves real-time WIP and cash flow visibility.
- Prioritizing quick invoice generation after work approval and weekly collections follow-up sustains healthier cash flow and reduces reliance on delayed batch billing.
Table of Contents
- What Makes Service Business Accounting Different From Product Accounting
- Core Accounting Practices Every Service Business Should Run Monthly
- Revenue Recognition, WIP, and Retainers: How to Record and Why It Matters
- Invoicing, Billing Cadence, and Collections: Practical Rules To Tighten Cash Flow
- Software and Workflows That Actually Solve Service-Firm Problems
- Chart of Accounts and Project Coding: A Setup Checklist
- Metrics and Reports To Watch Weekly and Monthly
- How an All-in-One Platform Simplifies the Accounting Workflow
- Tax Considerations Specific to Service Businesses
- Internal Controls and Fraud Prevention
- Handling Multi-State or Multi-Jurisdictional Tax Issues
- Budgeting and Forecasting for Growth and Seasonality
- Compliance Requirements and Regulatory Considerations
- Year-End Closing and Financial Statement Preparation
- When To Hire an Accountant or Outsource Bookkeeping
- The One Habit That Separates Healthy Service Firms From Fragile Ones
- Close the Quote-to-Cash Gap With One System
- Where To Go for Further Guidance
- Sources
- FAQ
What Makes Service Business Accounting Different From Product Accounting
Product businesses count boxes. Service businesses count hours, and hours don’t sit on a shelf waiting to be sold. That single fact changes almost everything about how the books should work.
Revenue in a service firm is tied to time and skill delivery, not inventory turns, so the moment you “earn” money and the moment cash lands in your account are two separate events, often separated by weeks. A practical accounting guide for professional services identifies this cash lag as running 30 to 60 days for most firms, which is exactly why a business can look profitable on paper and still struggle to make payroll.
Billing model makes this worse or better depending on how you structure it. Time-and-materials (T&M) engagements recognize revenue as hours are logged and approved. Retainers get paid up front but earned gradually, month by month. Fixed-fee projects sit somewhere in between, recognized as milestones or percentage-of-completion, depending on the contract.
The piece most owners miss entirely is work-in-progress, the value of labor and expenses already delivered but not yet invoiced. WIP is a real asset. It represents money you have already earned through actual work. If your books run on cash basis and you never track WIP, that asset is invisible, and your monthly profit and loss statement is quietly lying to you about how the business is actually performing. A firm can have a significant amount of delivered, billable work sitting unbilled and still show a mediocre month on the income statement, simply because nobody moved it from “work done” to “revenue earned.”
Core Accounting Practices Every Service Business Should Run Monthly
A service firm’s books go stale fast if nobody closes them on a schedule. Monthly close is not a big-company luxury. It’s the only way to catch a WIP problem or a billing gap before it becomes a cash crisis.
Run this checklist every month, in order:
- Bank reconciliation. Match every transaction against your bank feed before touching anything else.
- WIP reconciliation. Compare hours and expenses delivered against what’s been invoiced, and book the difference.
- AR aging review. Sort every open invoice into 0 to 30, 31 to 60, 61 to 90, and 90-plus day buckets.
- Deferred revenue check. Confirm retainer and prepayment balances still reflect unearned work.
- Payroll reconciliation. Verify labor costs posted to the correct project codes, not a generic payroll expense bucket.
Time and expense capture is where most of this falls apart before it even reaches the books. Set a firm rule: time gets entered and approved within 48 hours of the work, not batched at month-end from memory. Require every expense to carry a project code at the moment it’s submitted, not reconstructed later by a bookkeeper guessing which client a lunch receipt belongs to.
Project coding discipline decides whether your reports mean anything. Create a new project code any time you sign a new statement of work, not just for big engagements. Every hour, every subcontractor invoice, and every reimbursable expense should carry client, project, and service-line tags from day one.
Pro Tip: Build your close checklist into a recurring calendar reminder with a hard deadline, like the 5th business day of the month. A checklist nobody schedules is a checklist that quietly stops happening by month three.
- Approvals should happen weekly, not monthly, so errors get caught while people still remember the context.
- Coding conventions should be documented in one page your whole team can reference, not tribal knowledge held by one office manager.
- Payroll and time data should reconcile against each other, since a mismatch usually means someone logged hours to the wrong client.
Revenue Recognition, WIP, and Retainers: How to Record and Why It Matters
Under ASC 606’s five-step framework, you identify the contract, identify the performance obligations, set the transaction price, allocate that price across obligations, and recognize revenue as each obligation is satisfied. For most service engagements, that means revenue over time rather than at a single invoice date. T&M work typically recognizes as hours are delivered. Fixed-fee and milestone contracts recognize as percentage of completion or at defined checkpoints.
Here’s what that looks like in practice, in plain journal-entry terms:
- When work is delivered but not yet invoiced: debit WIP, credit earned revenue.
- When you issue the invoice for that work: debit accounts receivable, credit WIP (moving the asset from unbilled to billed).
- When payment arrives: debit cash, credit accounts receivable.
Retainers need separate handling entirely. A retainer payment is not revenue the day it lands in your account. It’s a liability, specifically deferred revenue, until you actually perform the work it’s paying for. Book the cash, credit deferred revenue, and only recognize revenue as you draw down against that balance through delivered work. Firms that book retainers as immediate income routinely overstate a strong month, and then face an ugly correction when the client’s prepaid balance runs dry and the work still isn’t done.
Firms that skip regular WIP tracking tend to understate performance in the months where delivery outpaces billing, according to Kantata’s analysis of revenue recognition in professional services. That understatement compounds. Managers who don’t see true monthly margin make staffing and pricing decisions based on numbers that were never accurate in the first place.
Invoicing, Billing Cadence, and Collections: Practical Rules To Tighten Cash Flow
Invoicing speed is the single biggest lever most service firms leave untouched. The fix isn’t complicated, but it does require breaking the habit of batching invoices at the end of the month.
- Tie invoice generation to time approval, not a calendar date. The moment a week’s hours are approved, that invoice should go out, not sit waiting for a monthly billing run.
- Bill weekly or biweekly wherever your contract terms allow it. A firm invoicing weekly collects meaningfully faster than one invoicing monthly, simply because the clock on payment terms starts sooner and more often.
- Design milestone invoices around real delivery points, not arbitrary calendar splits, so payment timing tracks actual earned revenue instead of drifting ahead of or behind the work.
- Structure retainer draws explicitly, showing the client exactly how much of their prepaid balance has been consumed each period, which cuts down on billing disputes before they start.
Collections need the same structure as billing. Set automated reminders at 7, 14, and 30 days past due, and review your AR aging buckets every week, not once a month. Any invoice crossing 60 days needs a phone call, not another email. Past 90 days, decide in advance whether that account goes to a collections partner or gets written off, and don’t let that decision drift by default.
Pro Tip: Put your retainer balance on every single invoice, even the ones that draw against it. Clients dispute far less when they can see the math themselves instead of taking your word for it.
Software and Workflows That Actually Solve Service-Firm Problems
Most accounting software was built for retailers counting inventory, not firms billing hours. Before choosing any platform, confirm it actually handles the mechanics unique to service delivery.
Require these core features, regardless of which platform you’re evaluating:
- Job-linked time tracking that ties every hour to a specific project code automatically, not through a manual export-and-match process.
- WIP reporting that shows unbilled value in real time, not just at month-end.
- Flexible invoicing that supports T&M, fixed-fee, milestone, and retainer billing without workarounds.
- Live bank feeds so reconciliation happens continuously instead of in a monthly scramble.
- Payroll sync so labor costs land on the correct project without duplicate data entry.
- AR dashboards that surface aging buckets and overdue accounts without building a spreadsheet by hand.
The integration pattern matters more than any single feature. Time and project data should flow into your accounting ledger, which should sync with payroll, which should connect to payment processing, which should feed your reporting. Every manual handoff between those systems is a place where errors creep in and a place where your numbers go stale.
| What to check | Why it matters |
|---|---|
| Mobile access | Field staff and account managers log time and expenses the same day, not from memory a week later |
| Single-login access | Fewer logins mean fewer skipped updates and less duplicate data entry across tools |
| Transparent pricing | Avoids surprise add-on costs that erode the margin you’re trying to protect |
| Data portability | You can export your data cleanly if you ever switch platforms |
A platform like Xero’s professional services guidance outlines this same feature set, and the takeaway holds regardless of vendor: pick for workflow fit, not brand recognition.
Chart of Accounts and Project Coding: A Setup Checklist
Most generic charts of accounts, the kind that come pre-loaded in off-the-shelf software, were built for retail or manufacturing. They have no home for WIP, no deferred revenue line, and no separation between the cost of delivering services and the cost of running the office. Fix this before you fix anything else in your books.
Add these account groupings if they’re missing:
- Work in progress as a current asset, distinct from accounts receivable.
- Deferred revenue as a liability, holding unearned retainer and prepayment balances.
- Service revenue categories broken out by service line, so you can see which offerings actually drive margin.
- Cost of services, separated cleanly from general and administrative expense, covering direct labor, subcontractors, and project-specific costs.
A chart of accounts built for service firms needs these accounts deliberately structured in from the start, not bolted on after the fact once someone notices the reports don’t make sense.
Project codes need a minimum set of fields to be useful: client, project, service line, and responsible manager. Apply these tags to every hour logged and every expense submitted, no exceptions, or your project-level profitability reports will have gaps that make the whole exercise pointless.
If you’re migrating from a generic template, map your old categories to the new structure before you touch live data, then run a full validation pass on your first month-end report. Check that WIP balances make sense, that no expenses landed in an unassigned bucket, and that project totals tie back to what you know actually happened that month.
Metrics and Reports To Watch Weekly and Monthly
Numbers only help if you’re checking the right ones. Five metrics tell you almost everything about a service firm’s health.
| Metric | Formula | What it reveals |
|---|---|---|
| Utilization | Billable hours ÷ available hours | Whether staff capacity is being used productively |
| Realization | Billed revenue ÷ standard rate value of hours worked | Whether you’re actually collecting your rack rate or discounting it away |
| Project margin | (Project revenue − direct project costs) ÷ project revenue | Whether individual engagements are actually profitable |
| Days sales outstanding (DSO) | (Accounts receivable ÷ total credit sales) × number of days | How long cash takes to arrive after work is billed |
| Overhead per billable employee | Total overhead ÷ number of billable staff | Whether your cost structure scales sustainably with headcount |
Check utilization and DSO weekly. Review project margin and overhead monthly, tied to your close process.
A 13-week cash forecast is the standard tool for bridging the gap between when work happens and when cash arrives, and it takes one spreadsheet tab to start: list expected receipts and payments week by week, update it every Friday, and watch for the weeks where the balance dips dangerously low before they arrive, not after.
Here’s a pattern worth knowing: when utilization looks strong but margin is falling, the problem usually isn’t effort. It’s staffing mix or subcontractor cost creep eating the difference between busy and profitable.
How an All-in-One Platform Simplifies the Accounting Workflow
Most of the friction in service business accounting doesn’t come from complicated rules. It comes from data trapped in five different systems that don’t talk to each other.
MyBizApps builds customer management, quotes, invoicing, scheduling, and accounting into a single mobile-first interface under one login. That structure directly addresses the handoff problem: when time tracking, invoicing, and the ledger live in separate tools, every transfer between them is a chance for a project code to get lost or a WIP balance to go stale.
- One login across quotes, invoicing, scheduling, and accounting means fewer places for data to get dropped between systems.
- Field teams can update job status and log time from a phone, so billing data reflects same-day work instead of a week-old memory.
- Businesses using an integrated invoicing and payment workflow often experience faster invoicing and payment cycles, which can positively impact cash flow.
Pro Tip: If your current setup requires exporting time data from one app and re-entering it into your accounting software, that manual step is exactly where WIP tracking quietly breaks down.
The fewer systems your team has to check, the less likely a billable hour disappears before it ever reaches an invoice.
Tax Considerations Specific to Service Businesses
Service firms face a different tax profile than product companies, mostly because there’s rarely inventory to complicate things, but there’s plenty else to watch.
Deductions worth tracking carefully include home office expenses if you run a small practice, mileage and travel for client work, professional development and licensing costs, subcontractor payments, and software subscriptions tied to service delivery. Keep receipts and mileage logs contemporaneously. Reconstructing a year of travel expenses in April is a losing exercise.
Estimated taxes catch a lot of service business owners off guard, particularly those newly self-employed or newly incorporated. If you expect to owe more than a modest amount at filing, quarterly estimated payments are typically required to avoid penalties. Your entity structure changes how this works. The IRS guidance on business structures explains how sole proprietorships, partnerships, S corporations, and C corporations each carry different tax treatment and filing obligations, and that choice ripples into how you handle owner draws versus payroll.
Single-member LLCs deserve specific attention here. IRS guidance for single-member LLCs clarifies that these entities are generally treated as disregarded for federal tax purposes unless you elect otherwise, which affects how owner distributions get reported and how bookkeeping should separate business funds from personal draws.
Sales tax rarely applies to pure labor services, but many states tax specific categories of services or bundled service-and-goods transactions. Check your state’s specific rules rather than assuming services are automatically exempt.
Internal Controls and Fraud Prevention
Small service firms often skip internal controls because “everyone trusts everyone,” which is exactly the environment where fraud tends to go unnoticed the longest.
Start with separation of duties. The person who approves invoices should not be the same person who reconciles the bank account. If your team is too small for a clean split, have an owner or manager review bank and credit card statements personally every month, line by line, rather than delegating that review entirely.
Require dual approval on any payment above a set threshold, and never let a single employee both add a new vendor and approve payment to that vendor. This single control closes off one of the most common fraud paths in small businesses: fictitious vendor schemes that run quietly for months before anyone notices.
Reconcile expense reports against receipts, not against an employee’s own summary. Review payroll changes, new hires, rate changes, and terminations, monthly against your HR records. And audit your project coding periodically. A pattern of expenses coded to vague or unusual project categories is often the first visible sign that something needs a closer look.
None of this requires a large team. It requires a handful of deliberate checkpoints that make casual fraud harder and honest mistakes easier to catch before they compound.
Handling Multi-State or Multi-Jurisdictional Tax Issues
Remote service delivery has made multi-state tax exposure a normal problem for firms that never used to think about it. If you have employees working from different states, or clients across state lines, you likely have obligations you haven’t mapped yet.
Nexus, the legal threshold that creates a tax obligation in a state, can be triggered by having an employee physically located there, even if your business is registered elsewhere. That employee’s presence can create state income tax withholding obligations, unemployment insurance registration requirements, and sometimes business registration requirements, regardless of where your clients are.
Client location matters too, particularly for any service categories a state chooses to tax. Some states tax specific professional or digital services; most don’t tax general labor. The rules vary enough that a blanket assumption in either direction is risky.
Track where your team physically works, not just where your company is registered. Maintain a simple internal map: state, employee count, registration status, and filing frequency. Update it whenever someone relocates or you hire in a new state.
This is one area where a qualified tax professional earns their fee quickly. Multi-state compliance mistakes tend to surface years later as penalties and back taxes, and by then the cost of getting it wrong dwarfs what proper setup would have cost upfront.
Budgeting and Forecasting for Growth and Seasonality
Service firms budget differently than product companies because the biggest cost driver, people, doesn’t scale in small increments. You can’t hire a third of a consultant.
Build your budget around capacity first. Start with expected billable hours per employee, apply your average realized rate, and that gives you a revenue ceiling before you even think about sales targets. Then layer in known seasonal patterns. Many service businesses see predictable slow periods, budget cycles that delay client decisions, or industries with hard seasonal windows.
Forecast hiring against a utilization trigger, not a calendar date. A common rule of thumb: when your existing team’s utilization stays above a healthy threshold for two consecutive months, that’s your signal to start recruiting, not after you’re already turning down work.
Run a rolling 12-month forecast alongside your 13-week cash forecast, updating both monthly. The 12-month view helps you plan hiring and major expenses; the 13-week view keeps you from running out of cash while you wait for that growth to pay off. Revisit both whenever you land or lose a client that materially changes your revenue base.
Build a modest cash reserve, ideally enough to cover a slow month or two, specifically to smooth over the gap between signing new work and collecting the cash from it.
Compliance Requirements and Regulatory Considerations
Compliance for service businesses depends heavily on industry and structure, but a few requirements apply broadly. Entity-level filings, whether that’s an annual report with your state or franchise tax obligations, need a calendar of their own, separate from your tax filing calendar.
Licensing is worth a fresh look every year. Many service categories, from consulting to skilled trades, carry state or local licensing requirements that need periodic renewal, and letting one lapse can jeopardize contracts with clients who require proof of active licensure.
If you carry professional liability or errors-and-omissions insurance, keep your coverage aligned with your actual client contracts. A contract that requires a coverage limit higher than your current policy is a gap that surfaces at the worst possible time, mid-dispute.
Payroll compliance deserves its own checklist: worker classification (employee versus independent contractor) gets scrutinized heavily, and misclassifying a contractor who functions like an employee creates real financial exposure. Review your classifications annually, not just when you first bring someone on.
Keep your bookkeeping records organized well enough to survive an audit without a scramble. That means retaining invoices, contracts, timesheets, and expense receipts in an organized, searchable system, not a shoebox of paper or a folder of unlabeled PDFs.
Year-End Closing and Financial Statement Preparation
Year-end close for a service firm follows the same monthly checklist, just with more scrutiny and a few additions. Start early, ideally in November, by reviewing your WIP balance and confirming every dollar of delivered-but-unbilled work is accounted for before the calendar flips.
Reconcile every account, not just cash: accounts receivable, deferred revenue, and any accrued liabilities like unpaid contractor invoices or year-end bonuses. Review your fixed assets and depreciation schedule if you have equipment or software capitalized on the balance sheet.
Your year-end financial statements should include a full profit and loss statement broken out by service line, a balance sheet that clearly shows WIP and deferred revenue as separate lines, and a cash flow statement that reconciles the gap between reported profit and actual cash movement. For a service firm, that last reconciliation often reveals the biggest surprises, since a strong profit year can still show tight cash if WIP and receivables grew faster than collections.
Close the books, then review them with a critical eye before filing anything. Compare year-over-year trends by service line and flag anything that moved sharply in either direction. That review is often where you catch a coding error that’s been quietly distorting reports for months.
When To Hire an Accountant or Outsource Bookkeeping
Most service business owners wait too long to bring in outside help, usually because bookkeeping feels like something you can keep doing yourself a little longer. The better signal isn’t revenue size. It’s complexity.
Bring in a bookkeeper once you’re managing multiple project codes, multiple billing models, or more than a handful of employees whose time needs tracking and reconciling weekly. A bookkeeping resource for service-based businesses notes that the priority for smaller firms isn’t finding the fanciest software. It’s finding a bookkeeping process that actually supports project coding and WIP tracking consistently.
Bring in a CPA once you’re making entity decisions, dealing with multi-state exposure, or facing estimated tax calculations you’re not confident about. A bookkeeper handles the monthly mechanics. An accountant handles the strategic and tax decisions that carry real financial consequences if they’re wrong.
Outsourcing doesn’t mean losing control of your numbers. Done well, it means someone with more bandwidth is running your monthly close on schedule while you focus on delivering the work that actually generates the revenue those books are tracking.
The One Habit That Separates Healthy Service Firms From Fragile Ones
After walking through every mechanism in this guide, one habit stands out above the rest: time-to-invoice discipline. Firms that bill within days of delivering work, reconcile WIP monthly, and run a rolling 13-week cash forecast rarely get blindsided by a cash crunch. Firms that batch invoicing and skip WIP tracking almost always do, eventually.
The real payoff isn’t cleaner books. It’s better decisions. Owners who trust their monthly numbers make faster, more confident calls on hiring, pricing, and which clients to keep. Owners who don’t trust their numbers hesitate, and hesitation is expensive in a service business where capacity is the whole product.
Start with the invoice cadence. Everything else follows from there.
— Philip
Close the Quote-to-Cash Gap With One System
Everything in this guide points to the same conclusion: the businesses with the cleanest books are the ones with the fewest handoffs between quoting, tracking time, invoicing, and reconciling the ledger. Every manual transfer between separate tools is where a project code gets lost or a WIP balance goes stale.
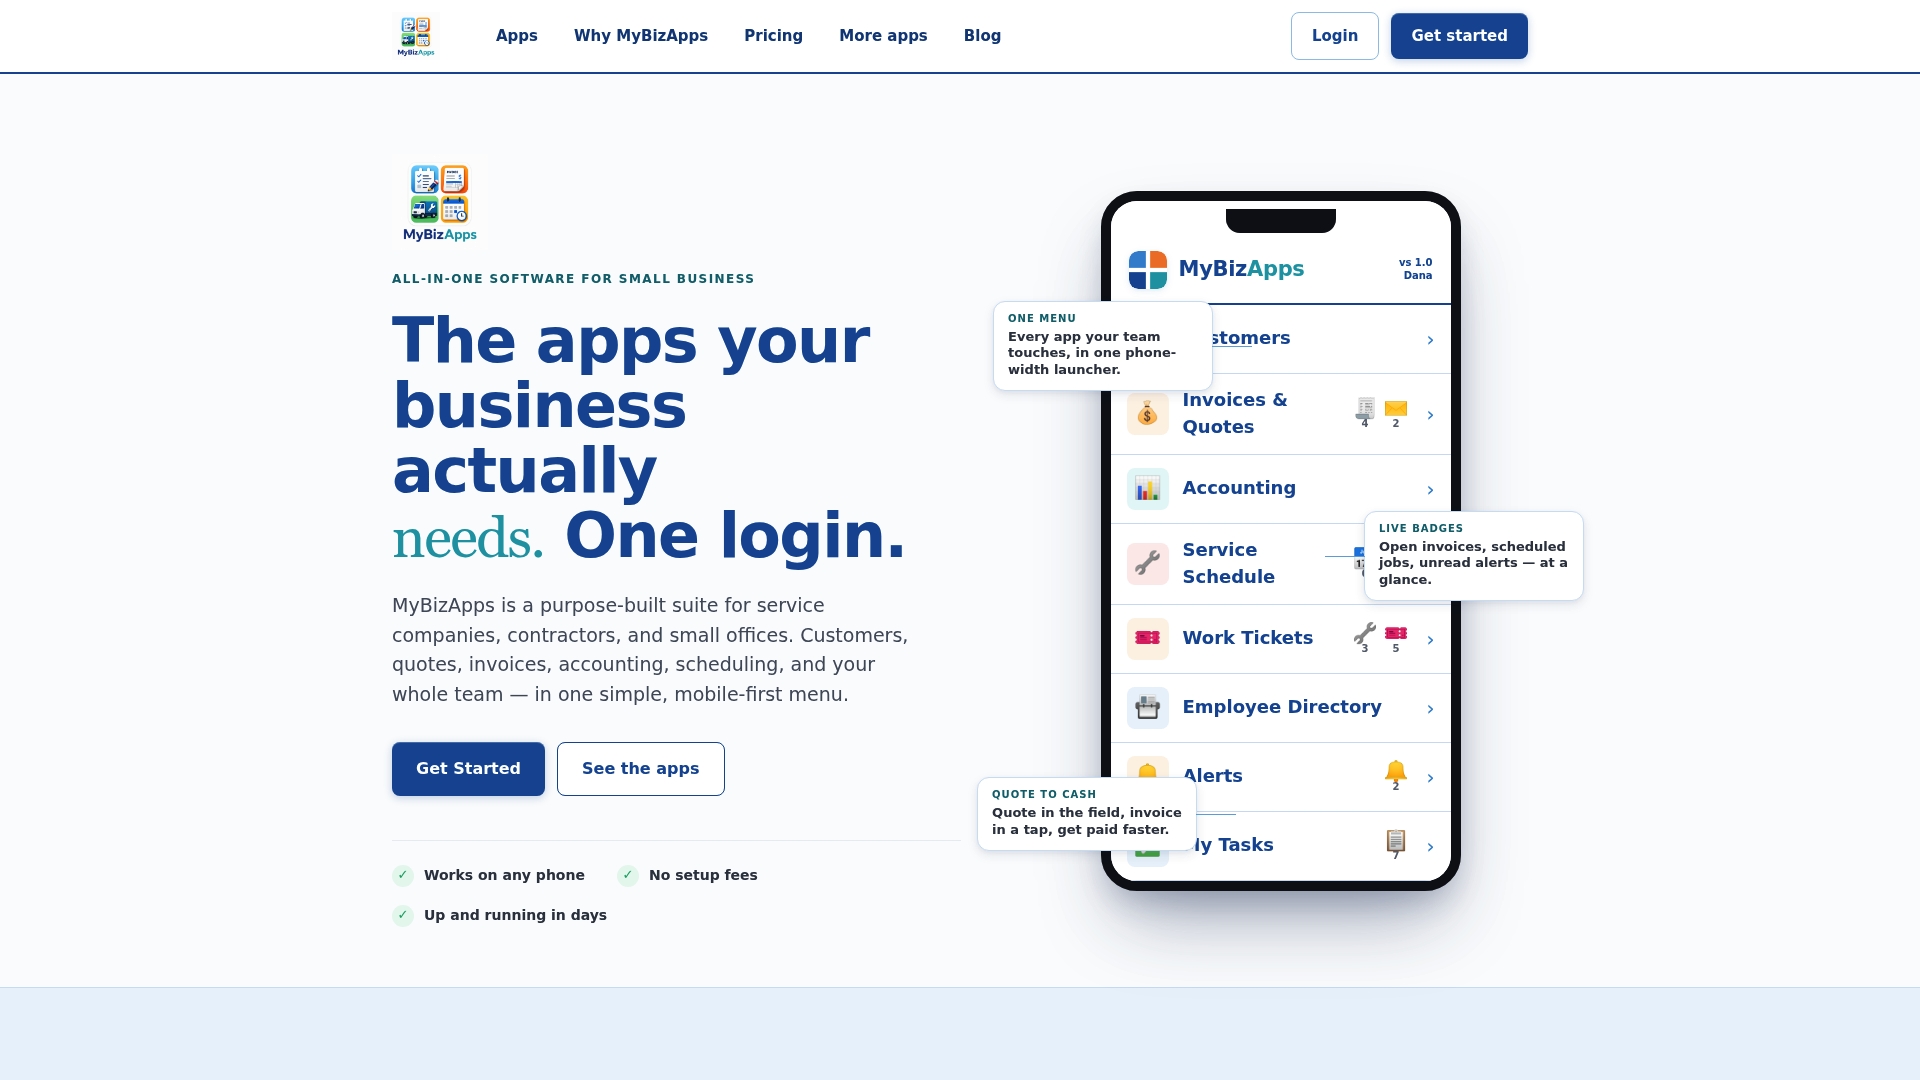
MyBizApps connects quotes, time tracking, invoicing, scheduling, and accounting under one mobile-first login, so the work your team logs in the field flows straight into an invoice without a re-entry step in between. That single-login structure is built specifically to solve the invoicing delays and WIP blind spots covered throughout this article, without requiring a separate app for every function. If your current setup means exporting data from one tool and retyping it into another, that’s the exact gap costing you cash flow every month.
Review the MyBizApps pricing plans or check the full price sheet to see which tier fits your team size and start closing that gap this week.
Where To Go for Further Guidance
For entity and tax structure decisions, the IRS business structures page and its single-member LLC guidance cover filing obligations directly. For WIP and revenue recognition mechanics, the Numetix professional services accounting guide and Steingard Financial’s 2026 guide go deeper into implementation. For cash-flow forecasting in a comparable operational context, Equibets’ guide to cash flow management offers a useful practical model, and MyBizApps’ own bookkeeping guide walks through monthly workflows in more detail.
Sources
- Business Structures | Internal Revenue Service
- Professional services accounting guide | Numetix
- Professional Services Accounting: 2026 Guide | Steingard Financial
FAQ
What Is the Best Accounting Software for a Service Business?
The best fit is whichever platform handles job-linked time tracking, WIP reporting, and flexible invoicing without manual workarounds. An integrated platform like MyBizApps reduces the handoffs between those functions since quotes, time, invoicing, and accounting share one login.
What Are the Seven Types of Accounting?
Common classifications include financial, managerial, cost, tax, auditing, forensic, and fiduciary accounting, though service firms mainly draw on financial and managerial accounting for day-to-day decisions. Which categories matter most depends on your entity size and whether you’re preparing statements for lenders, investors, or internal use.
What Is an Example of a Service Business?
Consulting firms, marketing agencies, law practices, contractors, IT support companies, and accounting firms themselves are all service businesses, since they sell time, expertise, and labor rather than physical inventory.
What Does a Sample Chart of Accounts Look Like for a Service Business?
A service-firm chart of accounts typically adds work-in-progress as a current asset, deferred revenue as a liability, service revenue broken out by service line, and cost of services kept separate from general and administrative expense. That structure lets you see true project margin instead of one blended number.
How Often Should a Service Business Reconcile WIP?
Monthly, at minimum, as part of the regular close checklist, though weekly spot checks on larger projects catch billing gaps before they compound into a bigger month-end surprise.